01
Audio & Video
Premium Audio & CTV
Podcast networks, streaming audio, broadcaster inventory, connected TV and premium video environments — the brand-building channels Chinese advertisers have historically had no clean route into.
China → World
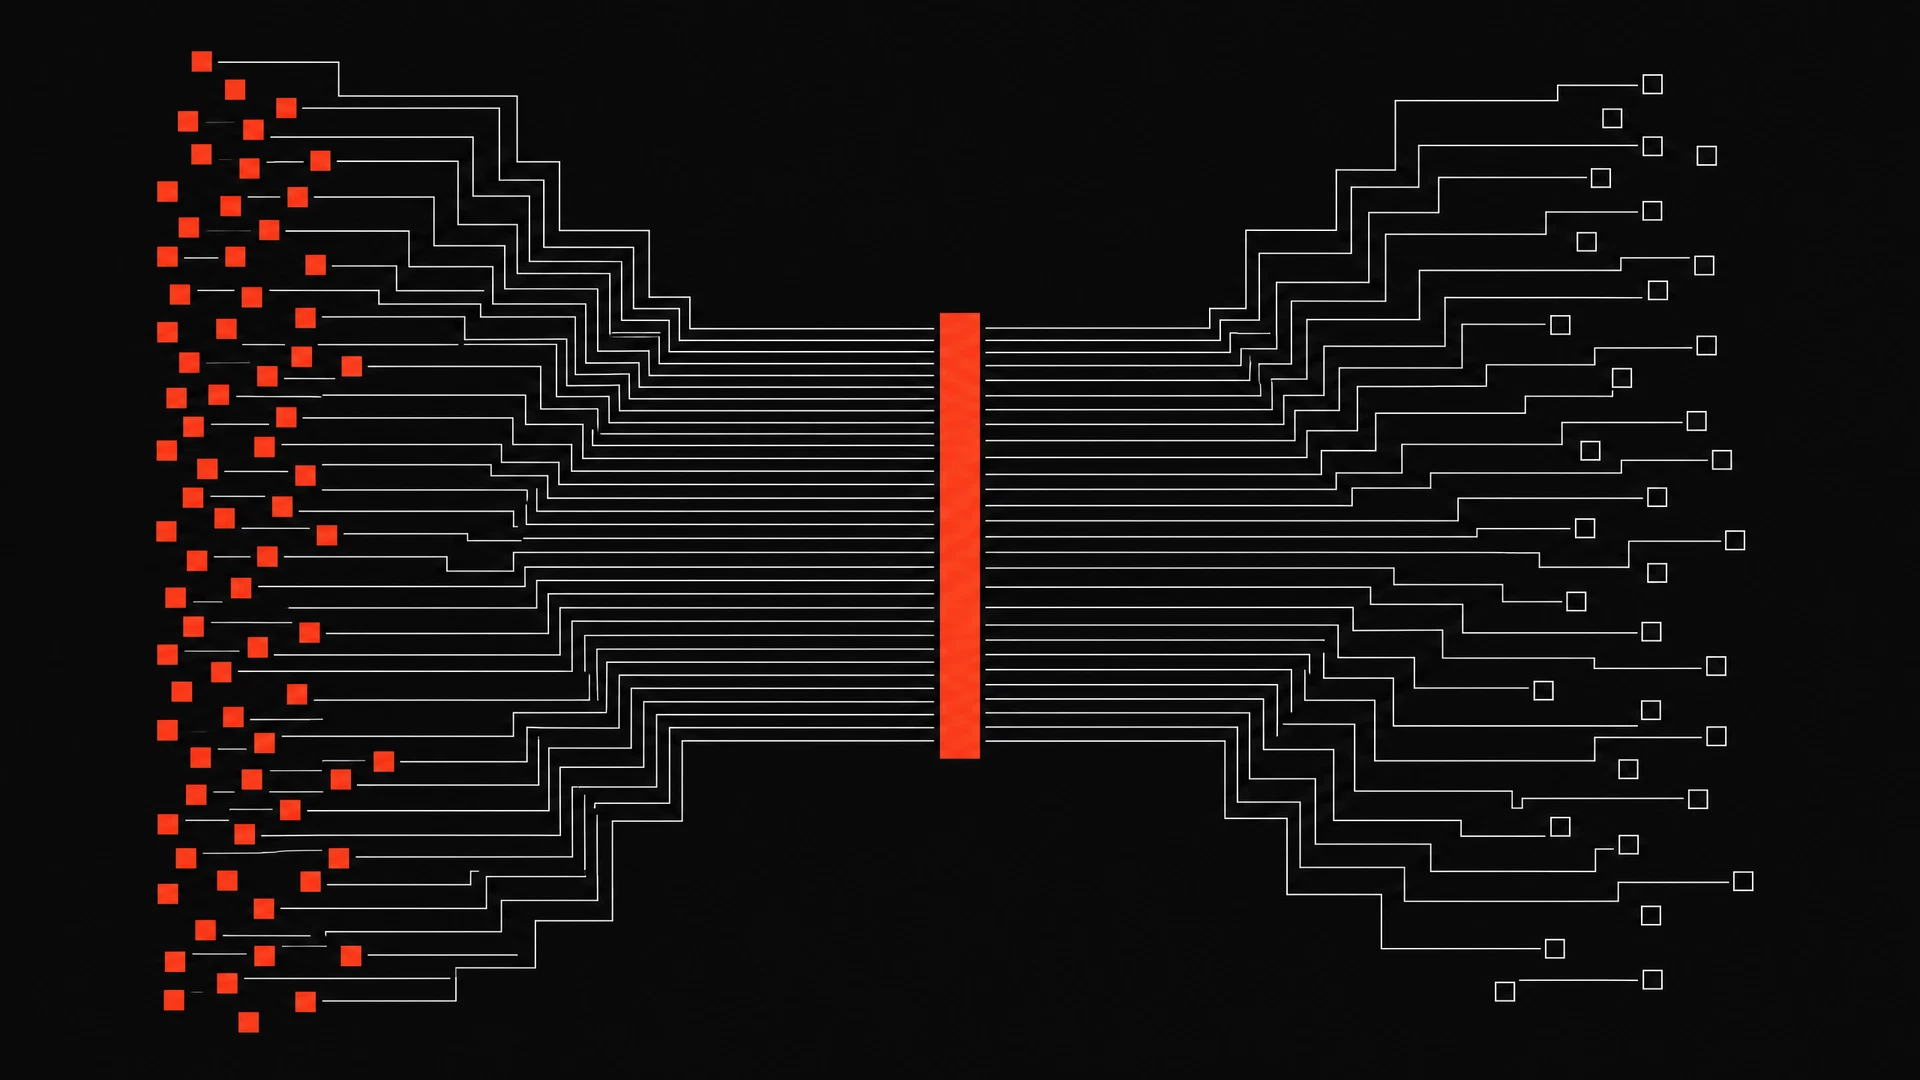
Chinese advertisers now command roughly a fifth of the global ad market, yet almost none of their outbound spend moves through infrastructure built for the job. Mammoth China Outbound is that infrastructure: one accountable operator connecting Chinese demand to global premium supply.
The gap, in numbers
Sources: ResearchAndMarkets China Digital Ad Spend Databook, 10 February 2026 · WPP Media, via Axios, 10 June 2025
The problem
Chinese outbound budget concentrates in Meta, Google and TikTok because those platforms are the only ones that are self-serve, RMB-billable and operable from inside China. Premium audio, connected TV, broadcaster and creator inventory has no equivalent route in, so it goes unbought regardless of advertiser appetite.
The constraint is structural, not strategic. A brand in Shenzhen with a global growth mandate can open a self-serve account and buy performance inventory the same afternoon. To buy a podcast network, a streaming audio package or premium CTV in the United States, that same brand needs a local entity, a compliant billing path, a verification standard its Chinese measurement stack recognises, and creative adapted for a market its team has never operated in.
Each of those is individually solvable and collectively prohibitive. The result is a market where demand is enormous and access is narrow — and where the missing piece is not another agency but an operator that owns the crossing itself.
Source: Reuters, 15 December 2025
What we open up
Three inventory families, each chosen because Chinese outbound advertisers want them and currently cannot buy them cleanly.
01
Audio & Video
Podcast networks, streaming audio, broadcaster inventory, connected TV and premium video environments — the brand-building channels Chinese advertisers have historically had no clean route into.
02
Talent
Localised creator ecosystems, celebrity partnerships and cultural amplification spanning Asia and the United States, including endorsement structures that run in both directions.
03
Performance
US and rest-of-world inventory that drives conversion immediately, plus programmatic and DSP connectivity so cross-border buying can scale inside systems agencies already operate.
Demand access
China outbound spend is concentrated in a comparatively small number of agencies and trading desks. Mammoth's founders held senior positions inside that layer, which is what makes the demand side addressable rather than theoretical.
For agenciesTier 1
BlueFocus · TecDo · MeetSocial
Tier 2
GIMC · Sevens · SparkX · Huntmobi · Eclicktech
Tier 3
4A agencies + 100+ specialists
Tiering reflects Mammoth's assessment of relative scale in the outbound market, compiled from founder relationships and public disclosures, 2026. Treat as directional.
The path
Each stage funds the next and increases defensibility. Revenue arrives early through representation; durability arrives later through owned rails.
Stage 01
Premium media relationships, inventory access and outbound partnerships generate revenue and establish commercial entry points on both sides of the border.
Creates the commercial beachhead
Stage 02
Inventory is embedded into the buying systems agencies already use, through DSP connectivity, localisation, creative adaptation and cross-border execution.
Embeds into agency workflows
Stage 03
Aggregated supply, a scalable activation layer and a proprietary marketplace convert accumulated access into durable platform leverage.
Owns the rails and the defensibility
Positioning
Mammoth China Outbound is not an agency, a reseller or a trading desk. It is a cross-border infrastructure layer that agencies, DSPs and media owners use to transact with each other across the China border. It does not compete with the parties it connects.
An agency selling campaign execution
A cross-border infrastructure layer for China outbound media
A reseller dependent on one-off inventory deals
A scalable access platform running from demand through to global supply
A trading desk competing for the same budgets
An enablement bridge for agencies, DSPs and media owners
Two sides, one crossing
Start here
Whether you hold Chinese outbound budget or global inventory that should be reaching it, the conversation starts the same way: what do you need moved, and where does it currently break?
Start with the reference material
What the category is, who operates in it, how budget actually moves, and where it breaks.
Read →Every figure we cite, with named sources and dates, in one place.
Read →Where Chinese advertisers can spend once the access problem is solved.
Read →